
Free advice
Practical guides for company directors
Clear, practical guidance on company deadlines, tax and the numbers behind your business.
Find the guidance you need
Starting a company
Sole trader or limited company: which is right for you?
A sole trader owns the business personally and is responsible for its debts; a limited company is a separate legal person. Choose by weighing risk, ownership,…
Read guide →
How to set up a limited company step by step
To set up a UK private limited company, choose its ownership, directors, name, registered office, SIC code and constitutional documents, then verify identities and register with…
Read guide →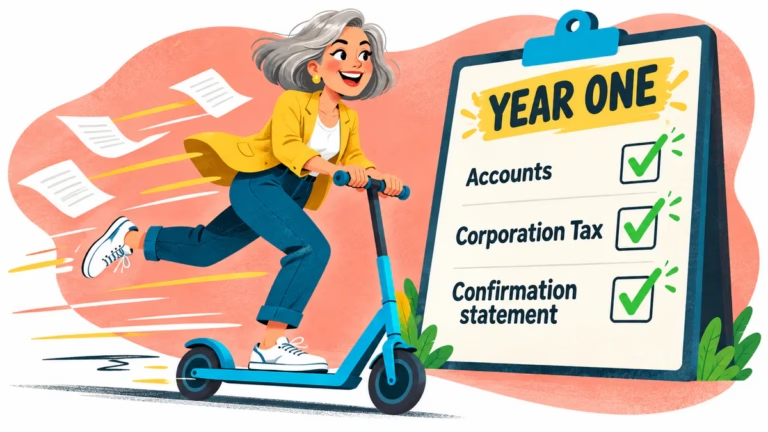
What happens after incorporation: your first-year checklist
After incorporation, secure the company documents, verify directors, open separate records and identify the trading start date. A private company normally files its first accounts within…
Read guide →
Company director duties in plain English
UK company directors have seven general duties under the Companies Act 2006 and remain responsible for records, accounts and filings even when work is delegated. Important…
Read guide →
Director identity verification: what you must do
Companies House identity verification became mandatory from 18 November 2025. A director verifies once, receives an 11-character personal code and uses that code to connect each…
Read guide →
Choosing your accounting year end
Companies House normally sets a new company’s year end to the last day of its incorporation anniversary month. A company can usually change it before accounts…
Read guide →
Registered office and service addresses explained
A registered office is the company’s public legal address; a service address is the public correspondence address for an individual director or PSC. Both may use…
Read guide →
Deadlines and compliance
UK company filing deadlines: the complete list
A private company normally files first accounts 21 months after incorporation and later accounts nine months after year end. Corporation Tax is usually paid nine months…
Read guide →
When are my first company accounts due?
A private company’s first accounts are generally due 21 months after incorporation. If they cover more than 12 months, the rule is 21 months from incorporation…
Read guide →
The confirmation statement explained
A confirmation statement confirms that Companies House information is correct. It is required at least every 12 months and must be filed within 14 days after…
Read guide →
Companies House late filing penalties and how to appeal
Late private-company accounts trigger automatic penalties from £150 to £1,500, depending on how late they are, and consecutive late years double the charge. File acceptable accounts…
Read guide →
Corporation tax deadlines: paying vs filing
Most small companies must pay Corporation Tax nine months and one day after their accounting period ends, but the Company Tax Return is due 12 months…
Read guide →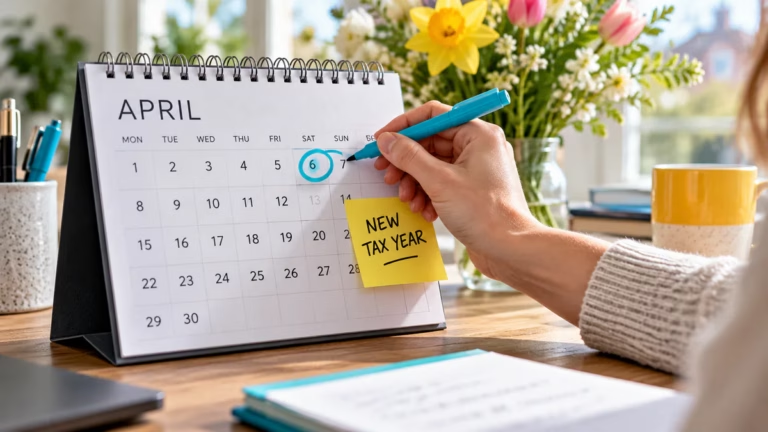
The UK tax year calendar
The 2026/27 tax year runs from 6 April 2026 to 5 April 2027. Important personal-tax dates include 5 October, 31 October, 31 January and 31 July,…
Read guide →
What happens if you miss a Companies House deadline
Late annual accounts bring automatic penalties starting at £150 and reaching £1,500 after six months, with doubled charges for two successive late years. Missing required accounts…
Read guide →
Dormant company accounts and obligations
A dormant company normally continues to file annual accounts and a confirmation statement with Companies House. It should tell HMRC when it is dormant for Corporation…
Read guide →Tax for directors
How to pay yourself: salary vs dividends
Owner-directors should plan salary and dividends together rather than assuming one is always better. Salary pays for work and goes through PAYE. Dividends are shareholder returns,…
Read guide →
Director's loan accounts explained
A director's loan account records money moving between a director and their company outside salary, dividends and expenses. If the director owes the company, the account…
Read guide →
Expenses you can claim through a limited company
A limited company may deduct revenue costs incurred wholly and exclusively for its trade, subject to specific exclusions and tax rules. Pay or reimburse only genuine…
Read guide →
Company pension contributions as a tax planning tool
Employer pension contributions for a director can reduce company taxable profit and do not create employee National Insurance when they qualify. They are not automatically tax-free:…
Read guide →
Corporation Tax rates and marginal relief
From 1 April 2026, Corporation Tax uses a 25% main rate and a 19% small-profits rate, with marginal relief potentially applying between £50,000 and £250,000 of…
Read guide →
Benefits in kind and the P11D
A benefit in kind is non-cash value provided by an employer to an employee or director, such as medical cover, a company car or an interest-free…
Read guide →
Do company directors need to file Self Assessment?
Company directors do not automatically need a Self Assessment return simply because they hold office. A return is required when HMRC issues a notice to file…
Read guide →Sole traders, landlords and MTD
Making Tax Digital for Income Tax: who, when and how
Making Tax Digital for Income Tax requires affected sole traders and landlords to keep digital records, send quarterly updates and complete their return through compatible software.…
Read guide →
Am I in MTD? The income thresholds explained
MTD for Income Tax applies to an in-scope sole trader or landlord when combined gross qualifying income exceeds the threshold for the test year. The thresholds…
Read guide →
MTD quarterly updates: deadlines and what to send
Standard 2026/27 MTD quarterly updates are due on 7 August 2026, 7 November 2026, 7 February 2027 and 7 May 2027. Each update reports cumulative digital-record…
Read guide →
Choosing MTD-compatible software
Choose MTD software only after confirming it appears on HMRC’s compatible-software list and supports every sole trade, property source, quarterly update and final-return task you need.…
Read guide →
Self Assessment deadlines and payments on account
For 2026/27, the usual online Self Assessment return and balancing payment are due by 31 January 2028, while the paper return is due by 31 October…
Read guide →
Allowable expenses for sole traders
Sole traders may deduct costs incurred wholly and exclusively for the trade, with separate rules for mixed use, capital purchases and disallowed spending. For 2026/27, compare…
Read guide →
Tax for landlords: the essentials
Individual landlords normally pay Income Tax on rental profit after allowable day-to-day expenses, while residential finance costs usually receive a basic-rate tax reduction instead of a…
Read guide →VAT
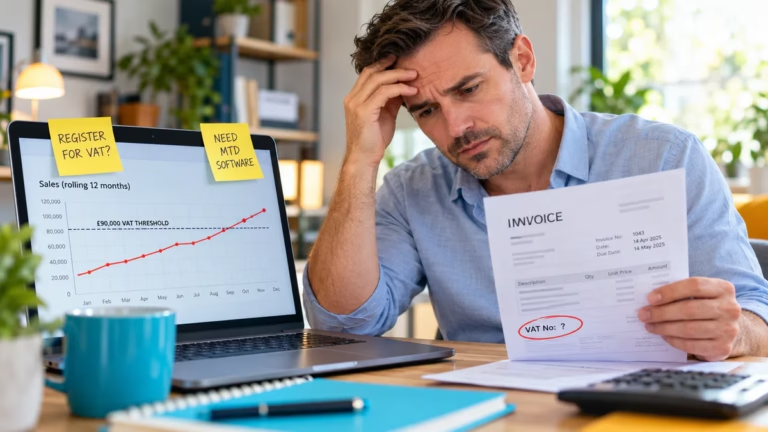
Do I need to register for VAT? The £90,000 threshold
For 2026/27, a UK-established business generally must register for VAT when taxable turnover exceeds £90,000 across the previous rolling 12 months, or is expected to exceed…
Read guide →
Flat Rate Scheme vs standard VAT
Standard VAT normally pays HMRC the VAT charged on sales less recoverable VAT on purchases. The Flat Rate Scheme instead applies a sector percentage to VAT-inclusive…
Read guide →
VAT deadlines and penalty points
For 2026/27, quarterly VAT returns and payments are usually due one calendar month and seven days after the period ends. Late returns build penalty points and…
Read guide →
VAT on imports, exports and online sales
Cross-border VAT depends on what is sold, where goods are located or services belong, whether the customer is a business, and who imports or facilitates the…
Read guide →
Voluntary VAT registration: pros and cons
A business below the compulsory threshold may register voluntarily when it makes or intends to make taxable supplies. Registration can recover eligible input VAT and may…
Read guide →Management information and growth
What management accounts are and why they matter
Management accounts are regular internal reports covering performance, cash, assets, liabilities and the outlook while owners can still act. Unlike annual statutory accounts, they are shaped…
Read guide →
12 KPIs every small business owner should track
A useful KPI set covers cash, profitability, demand, delivery and customer quality without creating unnecessary reporting. Start with the article’s 12 measures, define each one consistently…
Read guide →
Cash-flow forecasting in one afternoon
Start a cash-flow forecast with today’s cleared bank balance, then record when money should arrive and leave to produce a weekly or monthly running balance. A…
Read guide →
Building a budget you will actually use
A practical budget translates the operating plan into monthly assumptions for revenue, direct costs, overhead, cash and capacity, then compares actual results with the original plan.…
Read guide →
Pricing for profit: margin vs mark-up
Mark-up expresses profit as a percentage of cost, while margin expresses profit as a percentage of selling price. They are different: a 25% mark-up on a…
Read guide →
Writing a business plan a bank will read
A bank-ready business plan explains the business, its customers, its management, the funding required, how the money will be used and how cash will repay it.…
Read guide →Ready for a clearer next step?
Tell us what needs attention and we’ll explain how we can help.