
Benefits in kind and the P11D
A benefit in kind is non-cash value provided by an employer to an employee or director, such as medical cover, a company car or an interest-free…
Read guide →Free advice
Practical guidance, with links to the sources and relevant IFM services.
All guide topicsA benefit in kind is non-cash value provided by an employer to an employee or director, such as medical cover, a company car or an interest-free…
Read guide →
Employer pension contributions for a director can reduce company taxable profit and do not create employee National Insurance when they qualify. They are not automatically tax-free:…
Read guide →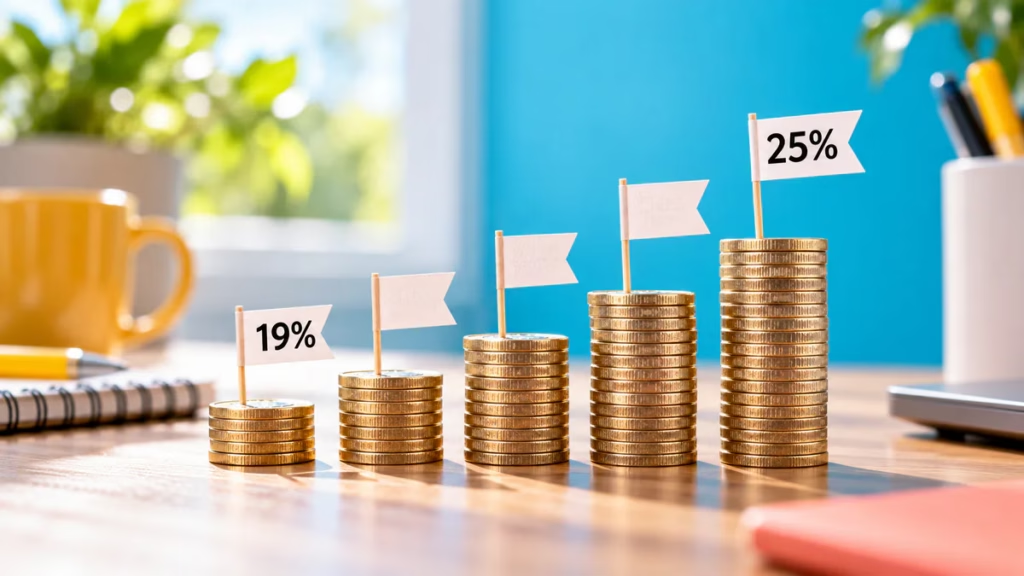
From 1 April 2026, Corporation Tax uses a 25% main rate and a 19% small-profits rate, with marginal relief potentially applying between £50,000 and £250,000 of…
Read guide →
A director's loan account records money moving between a director and their company outside salary, dividends and expenses. If the director owes the company, the account…
Read guide →
Company directors do not automatically need a Self Assessment return simply because they hold office. A return is required when HMRC issues a notice to file…
Read guide →
A limited company may deduct revenue costs incurred wholly and exclusively for its trade, subject to specific exclusions and tax rules. Pay or reimburse only genuine…
Read guide →
Owner-directors should plan salary and dividends together rather than assuming one is always better. Salary pays for work and goes through PAYE. Dividends are shareholder returns,…
Read guide →