Last reviewed: 29 September 2026 · Reviewed by IFM's qualified accountant
Businesses below the threshold may register voluntarily. Non-established businesses and some cross-border transactions follow different rules and may have no benefit from the UK threshold.
What taxable turnover means?
Taxable turnover includes sales that would be standard-rated, reduced-rated or zero-rated if the business were registered. Zero-rated sales count even though the VAT rate is 0%.
Exempt income is normally excluded, as are activities outside the scope of UK VAT, but classification requires care. A sale is not exempt merely because the customer is overseas or because no VAT was charged before registration.
Include the value before VAT of taxable supplies made by the person or legal entity. Do not deduct business expenses, purchases or profit margins.
What should you know about the rolling 12-month test?
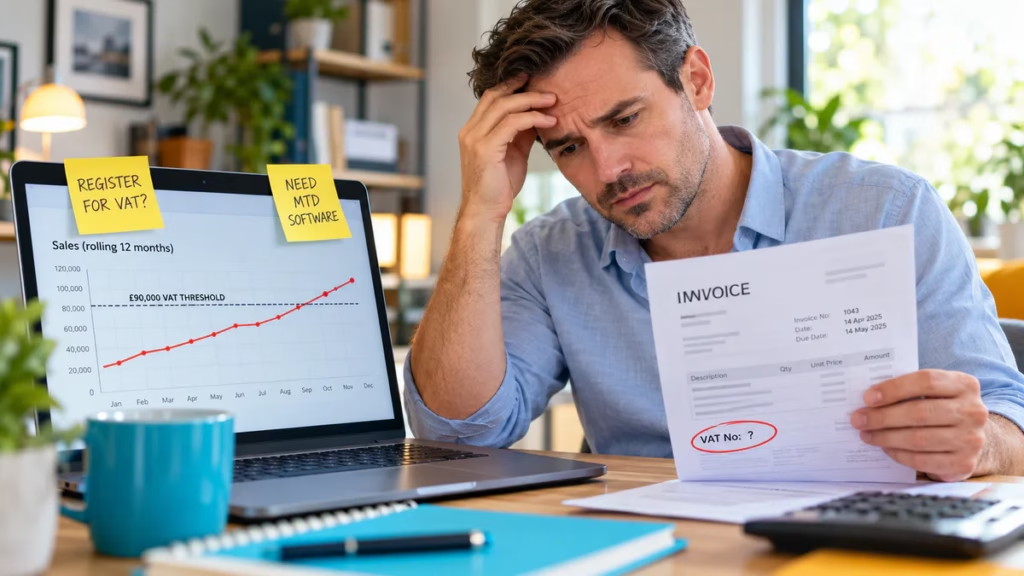
At the end of every month, total taxable turnover for the previous 12 months. If it exceeds £90,000 for 2026/27, the business normally has 30 days from the end of the month in which it crossed the threshold to notify HMRC. Registration usually takes effect from the first day of the second month after the threshold was exceeded.
This is not the accounting year, tax year or a fixed calendar year. Each new month drops the oldest month and adds the newest.
Keep a monthly schedule with sales by VAT liability. A fast-growing business should monitor weekly so pricing and invoices can change on time.
What should you know about the future 30-day test?
If at any time the business expects taxable turnover to exceed £90,000 in the next 30 days alone, it must normally register by the end of that 30-day period. Registration takes effect from the date the expectation arose.
This test catches a single large contract or launch. It is not a 12-month forecast. Document when the expectation became firm, the evidence available and the supplies involved.
Do not delay signing a contract solely to avoid acknowledging an expectation that already exists. Obtain advice before the transaction if the VAT clause or customer price is unclear.
What should you know about businesses and artificial separation?
The threshold applies to the taxable person, not each product line, trading name, website or bank account. A sole trader with several activities combines them.
Separate legal entities can have separate registrations, but HMRC can direct businesses to be treated together where activities have been artificially separated to avoid VAT. Financial, economic and organisational links are relevant.
Do not split customers, invoices or premises between connected entities without a genuine commercial and legal structure.
What should you know about registration date and charging VAT?
Charge VAT from the effective registration date, not merely the day the VAT number arrives. If invoices have already been issued, the business may need to issue VAT-only invoices or adjust pricing under the contract.
Until the VAT number is received, do not show a false number. The invoice can be amended once HMRC confirms registration. Ring-fence the VAT element so it is not spent.
The standard VAT rate is 20%, the reduced rate 5% and the zero rate 0% for 2026/27, but the correct liability depends on the supply. Some supplies are exempt or outside scope.
What should you know about pre-registration input VAT?
A newly registered business may recover VAT on certain goods bought in the four years before registration where the goods are still held or were used to make other goods still held, and on eligible services supplied in the six months before registration. All normal evidence and business-use rules apply.
These periods are not blanket rights. VAT connected with exempt activity, private use, cars or invalid invoices may be blocked or restricted. Prepare a schedule and retain invoices.
What should you know about voluntary registration?
A business below £90,000 can register voluntarily if it makes or intends to make taxable supplies. Advantages can include recovering eligible input VAT, presenting as VAT-registered and establishing systems before compulsory entry.
Costs include charging VAT to customers who cannot recover it, digital record keeping, returns, payment timing and error risk. A business selling mainly to VAT-registered customers may experience a different commercial effect from one selling to consumers.
Model prices, input VAT and administration. Voluntary registration is not automatically beneficial because purchases carry VAT.
What should you know about exemption from registration?
If the rolling threshold is exceeded but turnover is temporarily high and expected to fall below the deregistration threshold, HMRC may allow an exception from registration. It is not automatic and requires evidence.
The deregistration threshold is £88,000 for 2026/27. That lower number is not the compulsory registration threshold.
Apply promptly and continue on the assumption registration is required until HMRC agrees otherwise.
What should you know about overseas and cross-border complications?
A business not established in the UK can be required to register from its first UK taxable supply, without the £90,000 threshold. Goods imported, distance sales involving Northern Ireland, digital services and online marketplaces have separate rules.
The place-of-supply rules determine whether a service belongs in UK taxable turnover. Customer location and business status alone are not enough; exceptions apply by service type.
Obtain specialist advice before launching cross-border sales or storing goods in another country.
What should you know about after registration?
Use compatible software for Making Tax Digital for VAT, issue valid VAT invoices and file returns even when there is no VAT to pay. Most quarterly returns and payments are due one calendar month and seven days after period end, but confirm the VAT account.
Reconcile sales, purchase VAT, control accounts and the return before approval. Keep VAT records for the required period.
What should you know about a monthly threshold control?
Close sales by VAT category, calculate the rolling total and document excluded income. Add a 30-day forward check for signed contracts and known projects. Escalate when turnover approaches the threshold so prices and contracts can be reviewed before registration.
See VAT support for the relevant service page. Use the Deadline Finder for standard first accounts, first confirmation statement and Corporation Tax dates. For VAT, payroll, personal tax and other obligations, check the tax deadlines calendar and your official records.
What should you know about common threshold errors?
Do not test taxable profit, cash received or one financial year. Do not exclude zero-rated sales or divide one person's activities between trading names.
Review asset sales, grants, deposits and overseas income individually rather than applying one assumption. Keep a VAT-liability rationale for unusual or exempt supplies.
What should you know about if registration was late?
Notify HMRC promptly and establish the correct effective date. The business may owe VAT on sales from that date even if it did not charge customers, and penalties or interest can apply.
Review contracts to see whether VAT can be recovered from customers, issue corrected invoices where lawful and prepare the missing returns. A voluntary disclosure made with complete records is better than waiting for HMRC to identify the turnover.
What should you know about annual review?
Even after registration, monitor taxable turnover for scheme eligibility and possible deregistration. Confirm the £88,000 deregistration forecast test for 2026/27 and consider assets held before applying.
Retain the monthly rolling schedule and registration decision. If HMRC later asks when the threshold was crossed, contemporaneous figures are stronger than a reconstruction from annual accounts.
What should you read next?
Use the Deadline Finder for standard first accounts, first confirmation statement and Corporation Tax dates. For VAT, payroll, personal tax and other obligations, check the tax deadlines calendar and your official records.
What do people also ask about this topic?
What taxable turnover means?
Taxable turnover includes sales that would be standard-rated, reduced-rated or zero-rated if the business were registered. Zero-rated sales count even though the VAT rate is 0%.
What should you know about the rolling 12-month test?
At the end of every month, total taxable turnover for the previous 12 months. If it exceeds £90,000 for 2026/27, the business normally has 30 days from the end of the month in which it crossed the threshold to notify HMRC. Registration usually takes effect from the first day of the second month after the threshold was exceeded.
What should you know about the future 30-day test?
If at any time the business expects taxable turnover to exceed £90,000 in the next 30 days alone, it must normally register by the end of that 30-day period. Registration takes effect from the date the expectation arose.
What should you know about businesses and artificial separation?
The threshold applies to the taxable person, not each product line, trading name, website or bank account. A sole trader with several activities combines them.
Which official sources support this guide?
- https://www.gov.uk/vat-registration/when-to-register
- https://www.gov.uk/how-vat-works/vat-thresholds
- https://www.gov.uk/government/publications/budget-2025-overview-of-tax-legislation-and-rates-ootlar/annex-a-rates-and-allowances
General guidance, not advice for your situation.