Last reviewed: 29 September 2026 · Reviewed by IFM's qualified accountant
Use this checklist in order, then adapt it for the company's actual activity.
Which formation documents should you keep?
Save the certificate of incorporation, memorandum, articles, statement of capital, initial officer and PSC information, and evidence of the shares issued. Maintain the company's statutory records and board or shareholder decisions.
Keep the Companies House authentication code secure. It belongs to the company and is used for online filings. It is different from a director's personal identity-verification code.
Record who is authorised to make filings and who monitors the registered email and registered office. Companies House no longer relies on paper reminders in the way directors may expect, so email reminders and internal calendars matter.
How do you complete identity verification?
Every director needs to complete Companies House identity verification and connect the verified identity to each company role using the personal code. New directors provide the code as part of incorporation or appointment.
People with significant control also verify and provide their codes within the period that applies to them. A PSC who is also a director can have a different timing route from a PSC who is not.
Keep personal codes secure and share them only with someone trusted to file. Do not publish them in minutes or general company records.
How should you set up the company books?
The company must keep records that show money received and spent and its assets and liabilities. Tax records supporting the Company Tax Return generally need to be kept for six years from the end of the financial year, or longer in specified cases.
Set up:
- a company bank account;
- sales and purchase records;
- a clear expense process;
- records of money introduced or withdrawn by directors;
- asset and finance records;
- payroll and VAT control accounts where relevant; and
- a secure document-retention system.
Company money is not the director's personal money. Record salary, dividends, expense repayments and directors' loans according to what they actually are.
Why must you record the trading start date?
Incorporation and starting to trade can happen on different dates. HMRC uses the trading start in establishing Corporation Tax periods.
Activity can include selling, buying, advertising, employing someone, receiving income or otherwise carrying on the business. Preliminary work can require a closer look. Record the first activities and retain evidence rather than choosing a convenient date later.
If the company remains dormant, tell HMRC where appropriate and continue to meet Companies House accounts and confirmation-statement duties.
When should you add Corporation Tax services?
When the company becomes active, add Corporation Tax services to its business tax account and provide the required details, including the trading date. HMRC will give the accounting-period dates it holds.
Compare those dates with the Companies House financial year. The first statutory accounts often cover more than 12 months, but a Corporation Tax accounting period cannot. Two Company Tax Returns and payment dates may be needed within one first accounts period.
For a company below the instalment-payment rules, Corporation Tax is normally due nine months and one day after the accounting period. The return is normally due 12 months after it ends.
When does a new company need PAYE?
Register as an employer before the first payday where the PAYE rules require it. Directors can be employees or office holders, and the payroll treatment depends on the payment and circumstances.
Once the scheme is open, send a Full Payment Submission on or before payday and pay HMRC by the applicable monthly or quarterly deadline. Nil or irregular-payment periods may need reporting through the correct payroll submission rather than silence.
Set a payroll cut-off for hours, salary changes, starters, leavers and deductions.
When should the company consider VAT?
Monitor taxable turnover against the current VAT registration rules and consider whether voluntary registration is appropriate. The decision depends on customers, costs, pricing and administration, not simply whether VAT can be reclaimed.
If registered, keep digital records and use compatible software. Calendar the VAT quarter end and the usual return and payment date of one month and seven days later, subject to scheme exceptions.
How should you confirm ownership and decisions?
Make sure the register of members reflects the shares actually issued. Prepare and retain board minutes, shareholder resolutions and share certificates as appropriate.
If ownership, directors, addresses, PSCs or share capital change, check the event-driven Companies House filing rather than waiting for the annual confirmation statement. Some changes must be reported promptly through a separate form.
When is the first confirmation statement due?
Every company, including a dormant company, files a confirmation statement at least once every 12 months. The first review period normally ends 12 months after incorporation, and the filing is due within 14 days after that period.
The statement confirms the public record and the lawful intended future activities of the company. It is required even if nothing changed. Filing early creates a new review cycle, so update the calendar afterwards.
When are the first company accounts due?
Private-company first accounts are generally due 21 months after incorporation. Where the first accounts cover more than 12 months, the formal Companies House rule can be 21 months from incorporation or three months from the accounting reference date, whichever is longer.
Use the due date on the public register. Begin preparation well before it, leaving time for records, questions, tax calculations, director approval and correction of a rejected filing.
Which company details belong on websites and documents?
Business letters, order forms and websites must show the registered number, registered office, place of registration and the fact that the company is limited. Use the complete registered name.
If directors are named on business letters, all directors must be named. Invoices have additional requirements.
How should you protect information and arrange insurance?
Assess data-protection obligations and whether the ICO data protection fee applies. Put privacy information, security processes and processor contracts in place before collecting customer or employee information.
Arrange insurance appropriate to the activity, which may include employers' liability, public liability, professional indemnity or industry-specific cover. Incorporation does not replace insurance.
What should you review after the first quarter?
After three months, check that the bank reconciles, invoices and costs are recorded, director transactions are classified, taxes are registered and reminders reach more than one responsible person. Correcting the process early is easier than rebuilding a year.
Test the process as well as the records. Confirm who opens Companies House and HMRC messages, who approves payments, who supplies bookkeeping documents and who acts when the usual person is away. A small company can have sound software and still miss a deadline because responsibility was assumed rather than assigned.
Compare actual trading with the original plan. A faster start may bring VAT, payroll, cash-flow or funding questions forward. A delayed start may mean HMRC should still regard the company as dormant for Corporation Tax. Record the conclusion and the evidence used.
Before the year end, agree a timetable for reconciliations, supporting schedules, draft accounts, director review and tax work. Starting before the statutory due date protects time for questions and corrections.
Use the Deadline Finder for standard first accounts, first confirmation statement and Corporation Tax dates. For VAT, payroll, personal tax and other obligations, check the tax deadlines calendar and your official records.
What should you read next?
Use the Deadline Finder for standard first accounts, first confirmation statement and Corporation Tax dates. For VAT, payroll, personal tax and other obligations, check the tax deadlines calendar and your official records.
What do people also ask about this topic?
What should I do immediately after incorporating a company?
Save the incorporation documents, confirm shares and PSC records, secure filing credentials and start bookkeeping before transactions accumulate. Open a company bank account, record any personal payments correctly and decide who monitors the registered office, registered email and Companies House deadlines.
When must a new company register for Corporation Tax?
A company must tell HMRC when it becomes active for Corporation Tax, normally within three months of starting business activity. Incorporation and trading are not necessarily the same date. Preserve evidence of the first activity and use the date shown in HMRC records when planning returns.
Does a new limited company need a separate bank account?
The law treats the company as a separate person, so company and personal money should be kept clearly separate. A dedicated account provides cleaner evidence and helps prevent drawings being misclassified. If a director pays an early cost personally, record it through the director’s account with the receipt.
What filings are due in a company’s first year?
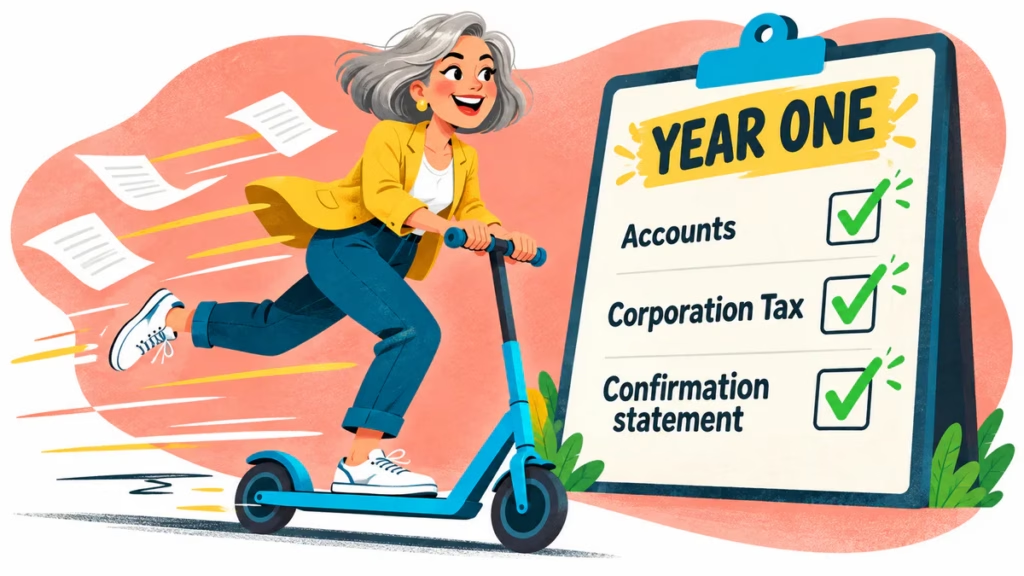
The first confirmation statement review period normally ends 12 months after incorporation and filing is due within 14 days. First accounts are generally due 21 months after incorporation. Corporation Tax, PAYE or VAT dates depend on when the company starts activity and which registrations apply.
Which official sources support this guide?
- https://www.gov.uk/running-a-limited-company
- https://www.gov.uk/prepare-file-annual-accounts-for-limited-company
- https://www.gov.uk/guidance/filing-your-companys-confirmation-statement
General guidance, not advice for your situation.